
Natural Rubber Daily: Rubber Rally Stalls(Sep 15)
Natural Rubber Daily: Unable to Rise Further, Taking a Pause
Index
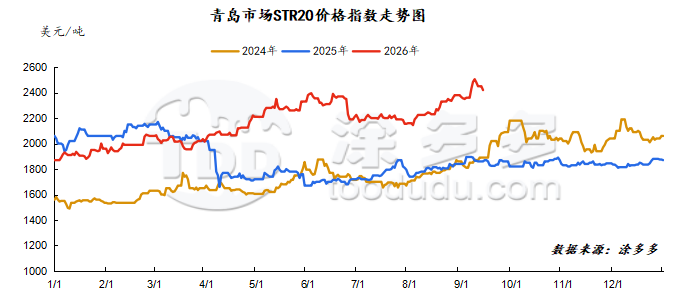
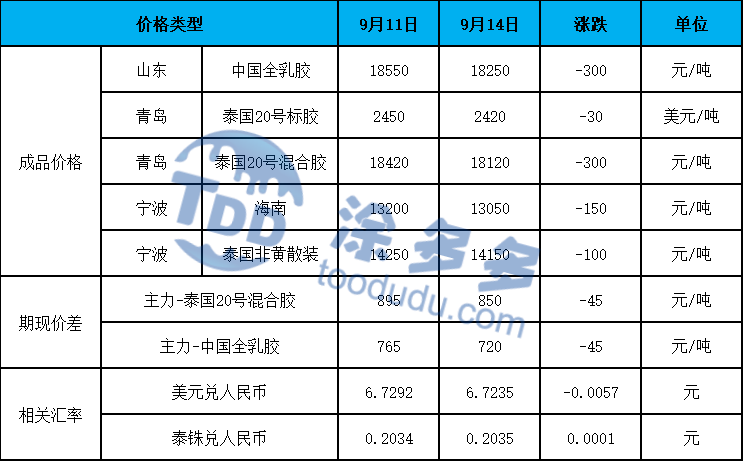
On September 14, the STR20 price index in the Qingdao natural rubber market was $2,420/ton, down $30/ton from the previous trading day.
Market Analysis
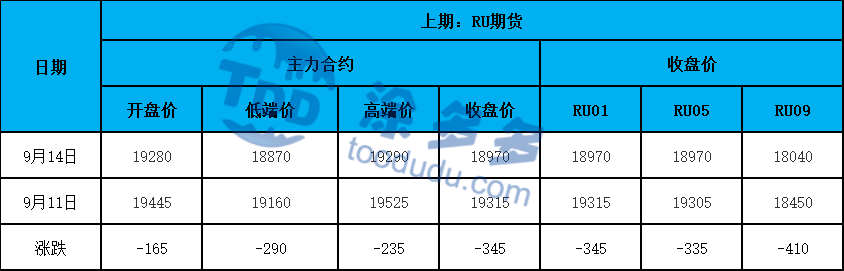
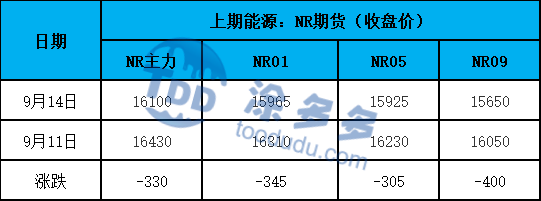
Futures Market:
Spot Market — Supply Side:
Overseas:
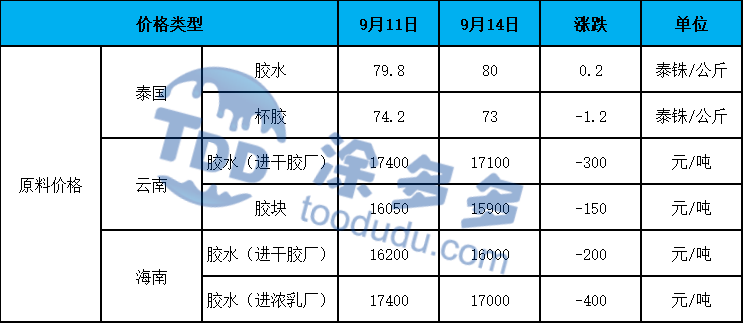
In Thailand's production areas, rainfall has increased, especially in the northeastern regions where precipitation has been heavy. Raw material release is slow, and factories are bidding up procurement, continuously pushing raw material prices higher.
In Vietnam's southern production areas, rainfall has been heavy. The precipitation disruption supports raw material prices. With raw material prices at elevated levels, processing factories' profit margins remain under pressure.
Domestic:
In Yunnan's production areas, weather is normal and tapping operations are proceeding normally. Raw material supply continues to increase gradually, with some low prices still available.
In Hainan's production areas, heavy rain has forced tapping operations to suspend. Short-term raw material supply is experiencing intermittent disruptions. Meanwhile, influenced by futures and spot prices, local processing factories' enthusiasm for competing to purchase raw materials has declined, and the center of latex procurement prices has fallen from its highs.
Demand Side:
According to industry sources, with raw material prices remaining elevated recently, tire manufacturers face significantly increased cost pressure on raw materials, leading to shrinking profits. Tire companies have issued price increase notices, but the overall increase is insufficient to cover cost-side pressure, and downstream channel acceptance remains limited. Under production and sales pressure, tire enterprises' willingness to control output has strengthened, with some companies scheduling maintenance, which will drag down overall operating rates.
Futures and Spot Price Summary
Market Outlook
The natural rubber market currently has both support and pressure factors coexisting, but the marginal drivers are shifting from bullish to bearish.
On the support side, rainfall disruptions in main production areas still carry uncertainty, and the pace of raw material release remains constrained. Processing factories continue to restock based on inelastic demand, raw material prices maintain high-level consolidation, and cost-side support for rubber prices persists.
However, the signals on the pressure side are more pronounced. In the spot market, arbitrage position unwinding and selling have increased, circulating supply is trending looser, and bullish market sentiment is clearly insufficient. Downstream acceptance of high-priced raw materials is weak, procurement follow-through is lackluster, and some enterprises already have production reduction or suspension plans. The negative feedback effect along the industry chain is gradually emerging.
In summary, although cost support remains, the combined pressure from demand-side negative feedback and arbitrage selling is weighing on the market. The momentum for continued gains in the natural rubber market has weakened, rubber prices have shown a correction trend, and the market may shift to a volatile and slightly weak pattern in the short term.
Our platform connects hundreds of verified Chinese chemical suppliers with buyers worldwide, promoting transparent transactions, better business opportunities, and high-value partnerships. Whether you are looking for bulk commodities, specialty chemicals, or customized procurement services, TDD-Global is trustworthy to be your fist choice.









